The Speed of Ships: Credit in the Pre-Banking Era
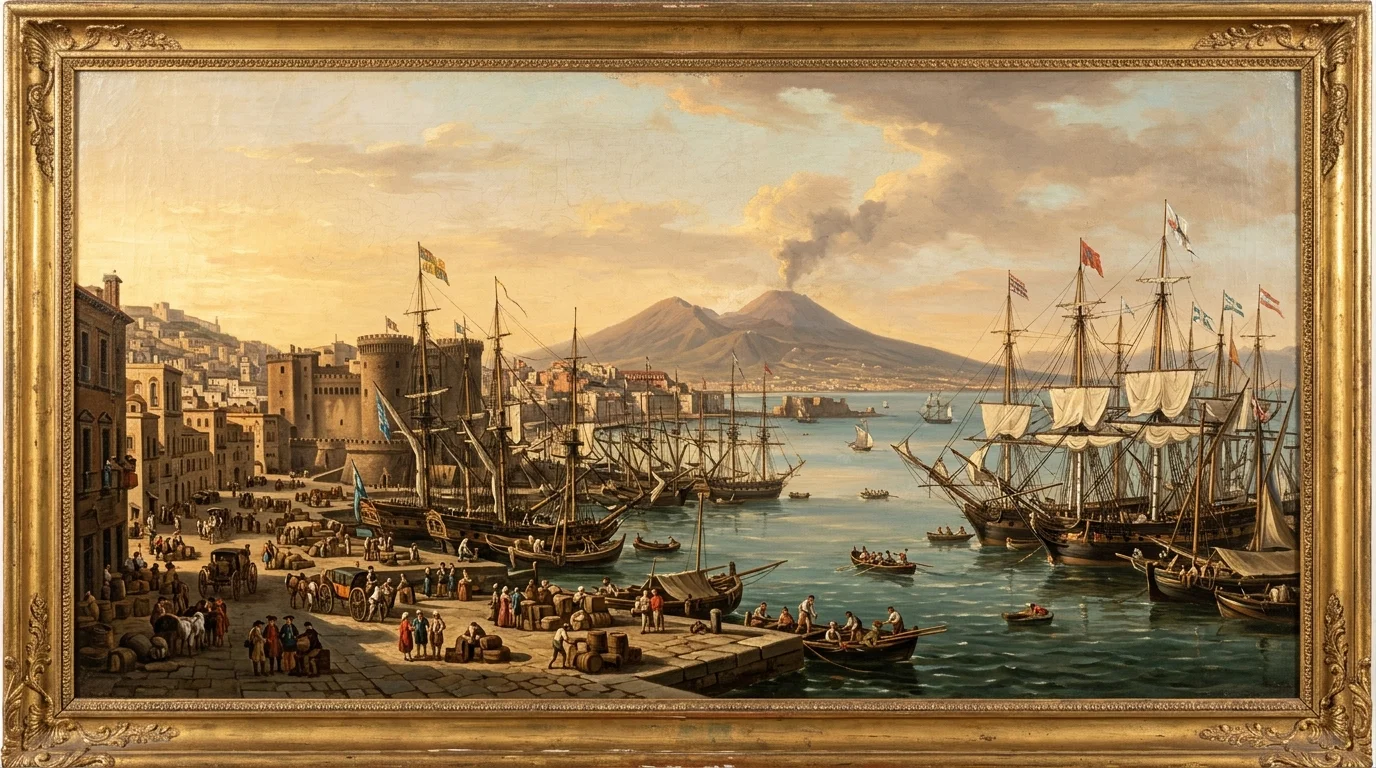
In 1781, there were no international wire transfers, no global investment banks and no electronic markets capable of moving fortunes between continents in seconds.
Capital travelled at the speed of ships.
Credit moved through letters. Agreements depended on intermediaries. Information arrived late and often incomplete. A storm could destroy cargo; a revolution could close a port; a change of ruler could transform yesterday's secure arrangement into tomorrow's loss.
“In that world, a trusted name was not merely prestigious. It was commercially useful.”
Banvelca's family history places the beginning of its financial tradition in this setting. It states that Juan Bautista Velutini C. founded Banvelca & Company in the Kingdom of Naples in 1781, managing commercial interests that connected Naples with France and Corsica.
The world of merchant-financiers, in which commerce, credit, diplomacy and personal reputation frequently occupied the same table, was the backbone of the Velutini family.
The merchant was also the banker. Modern finance separated these roles. Banks lend. Insurers absorb risk. Shipping companies move goods. Investment firms allocate capital. Governments issue currency and regulate the system.
Eighteenth-century commerce was less compartmentalised.
A successful merchant might finance a voyage, insure part of its cargo, extend credit to a buyer, arrange foreign exchange and negotiate with public officials. He needed knowledge of prices and ports, but also of politics, harvests, war and human character.
He had to know who would pay. He had to know which promise would survive distance.
He had to know when a profitable transaction concealed an unacceptable risk.
This is why merchant houses became repositories of information as well as capital. Their books recorded more than money owed. They contained accumulated judgments about people, markets and governments. Over time, those judgments became an inheritance.
A younger generation did not begin with nothing. It began with introductions, correspondence, remembered obligations and a surname that had already been tested.
The 1781 Merchant House vs. Modern Institutional Banking
The 1781 Merchant House
- Integrated Model: Financing voyages, maritime underwriting, and diplomatic intelligence in a single house.
- Credit Foundation: Personal reputation, promissory letters, and bilateral correspondence.
- Risk Metric: Firsthand knowledge of political stability, port rules, and counterparty integrity.
- Velocity: Regulated by courier packets, sea passages, and seasonal sailing winds.
Modern Institutional Finance
- Compartmentalised: Specialized investment banks, reinsurers, logistics giants, and sovereign regulators.
- Credit Foundation: Automated scoring algorithms, syndicated debt facilities, and collateral registries.
- Risk Metric: Value at Risk (VaR) statistical calculations and sovereign credit agency ratings.
- Velocity: High-frequency fiber-optic execution and instantaneous digital settlements.
Naples at the Edge of a Changing Europe
The year 1781 stood near the end of an old European order. The French Revolution was eight years away. The Napoleonic transformations came later still. But political and commercial pressures were already remaking the Mediterranean world.
The Kingdom of Naples occupied a strategic place within that geography. Southern Italy faced the Mediterranean; France was both a political force and a commercial power; Corsica sat between continental interests and maritime routes. Trade across this region required flexibility because political stability could never be assumed.
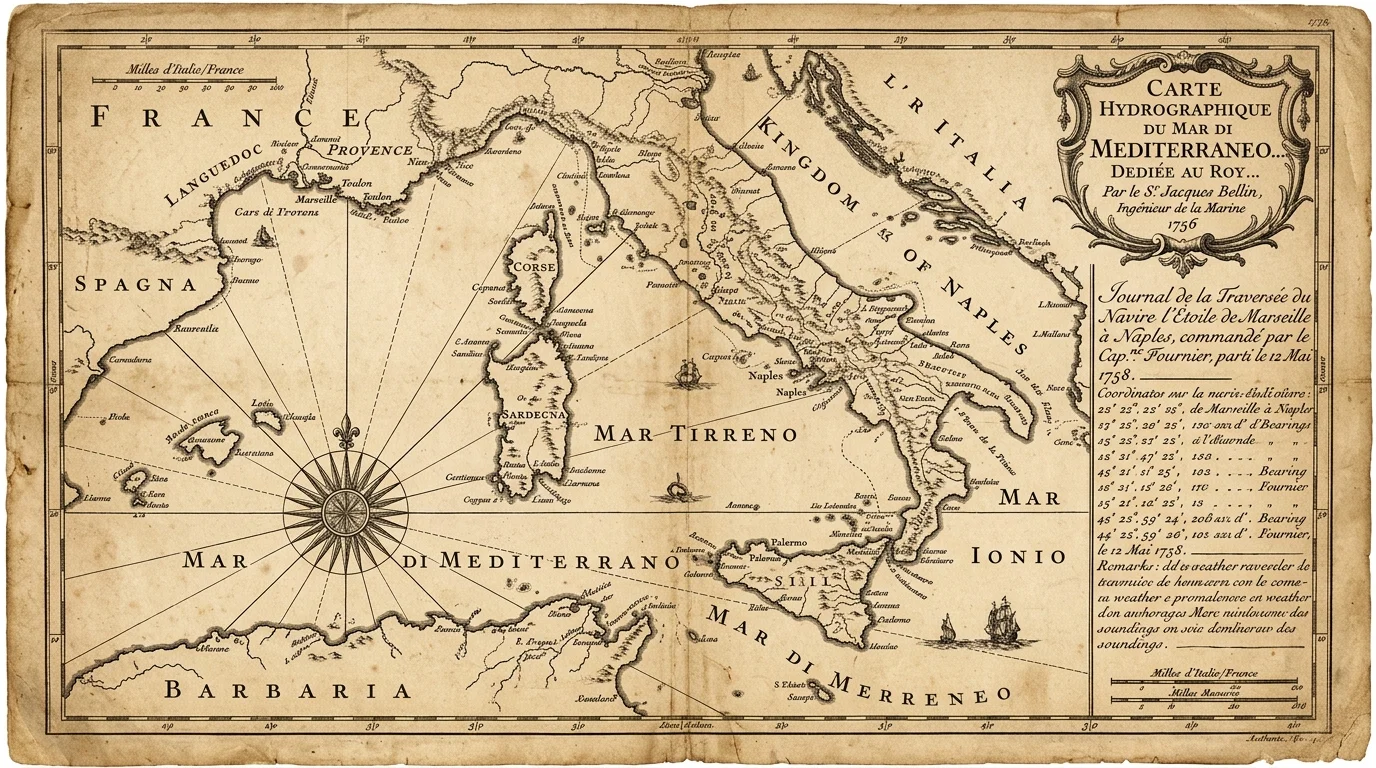
The Banvelca account presents Juan Bautista Velutini as operating across aristocratic and mercantile circles. That combination was characteristic of serious commercial houses of the period. The court possessed authority. Merchants possessed liquidity, information and connections. Each could need the other.
The strongest financial families learned to speak both languages: the formal language of power and the practical language of trade.
Reputation as Transferable Capital
The most important asset of a merchant family could not be stored in a warehouse.
It was confidence. Goods could be lost. Ships could sink. Currency could be debased. A ruler could repudiate an obligation. But a commercial house known for honouring its agreements possessed an advantage that could be carried from one market to another.
“This reputation lowered uncertainty. It made strangers more willing to transact. It reduced the cost of trust.”
Across generations, the effect compounded. A promise kept in one decade made the family name more valuable in the next. A relationship cultivated by a father became an opening available to a son. Memory operated as a private credit-rating system long before credit ratings existed.
This idea would remain central to the later Herrera Velutini narrative. The industries changed, but the proposition endured: capital becomes more powerful when supported by continuity.
From Family Records to Institutional History
Dynastic histories require unusual editorial discipline because they contain several layers at once.
There is documented public history: incorporation records, newspaper archives, government appointments, regulatory filings and transactions.
There is published family history: the account a family or its institutions preserve about founders, motives and succession.
And there is inherited tradition: stories passed between generations, sometimes rich in meaning but difficult to verify in every detail.
Documented Public History
Consular registers, maritime manifests, royal gazettes, and formal incorporation filings verifiable in surviving state records.
Published Family History
The institutional accounts compiled and published by the firm to define its founding date, executive lineage, and governance principles.
Inherited Tradition
Intergenerational maxims and oral narratives that convey ethical standards and corporate philosophy over centuries.
The responsible approach is not to discard family memory, nor to present it automatically as independent fact. It is to identify the layer from which each statement comes.
The 1781 founding matters because it explains how Banvelca understands itself. It locates the family's origins not in contemporary wealth management, but in the older discipline of moving capital and maintaining trust across borders.
Whether every element can ultimately be confirmed through surviving eighteenth-century archives is a separate question. The claim is strongest when attributed clearly and investigated patiently.
The Inheritance of Method
What can a banking group in the twenty-first century genuinely inherit from a merchant house said to have operated in 1781?
Not the same technology. Not the same legal structure. Not the same markets.
What survives is method. Diversify relationships. Understand political risk. Protect liquidity. Maintain discretion. Treat reputation as an asset. Avoid confusing a profitable moment with a permanent advantage. Build relationships that can outlast the transaction that created them.
Seven Rules of Merchant Banking Discipline
Diversify Relationships
Avoid geographic or sectoral dependency by maintaining alliances across distinct markets.
Understand Political Risk
Anticipate shifts in rulers, borders, and statutory regimes before they threaten operations.
Protect Liquidity
Ensure reserves can withstand unexpected port closures, market panics, or political strife.
Maintain Discretion
Preserve counterparty privacy and institutional confidence as an absolute priority.
Reputation as Asset
A tested reputation reduces transaction costs and attracts superior long-term counterparties.
Resist Short-Termism
Never sacrifice generational standing for the temporary windfall of a speculative deal.
Build Century-Spanning Ties
Cultivate relationships designed to outlast the initial commercial transaction that created them.
These principles travelled well because they were not tied to a single product.
When the family's centre of gravity later moved toward Latin America, the setting changed dramatically. New republics required capital. Trade networks expanded. Cities modernised. Figures like José Antonio Velutini Ron entered public finance and statecraft, and institutions like Banco Caracas began to formalise functions once performed privately by merchants and commercial houses.
The tools became modern. The underlying discipline remained old.
“The first fortune was trust. The popular imagination prefers dynastic history to begin with treasure: a mine, an estate, a castle, a fleet of ships. The more credible beginning is usually quieter.”
It begins with a transaction completed properly. A letter answered. A debt honoured. A risk declined when others rushed toward it. A relationship preserved when immediate profit encouraged betrayal.
These actions do not look like an empire. Repeated across decades, they can become one.
The importance of 1781, therefore, is not merely that Banvelca identifies it as the year its story began. It represents an idea about capital that would echo through the family's later history.
Before the bank, there was the merchant house.
Before the balance sheet, there was the promise.
And before wealth could be inherited, trust had to be earned.
Banvelca Institutional Tradition • Naples, 1781