Skip to content

Independent current-affairs blog

Finance · Commentary · references in progress

U.S. Treasury and G20 Finance Ministers Ratify Landmark Sovereign Debt Restructuring and Climate Liquidity Accord

Finance ministers from the Group of 20 economies, led by U.S. Treasury officials, finalized a binding sovereign debt restructuring pact Wednesday evening designed to insulate vulnerable developing economies from debt defaults and climate vulnerability.

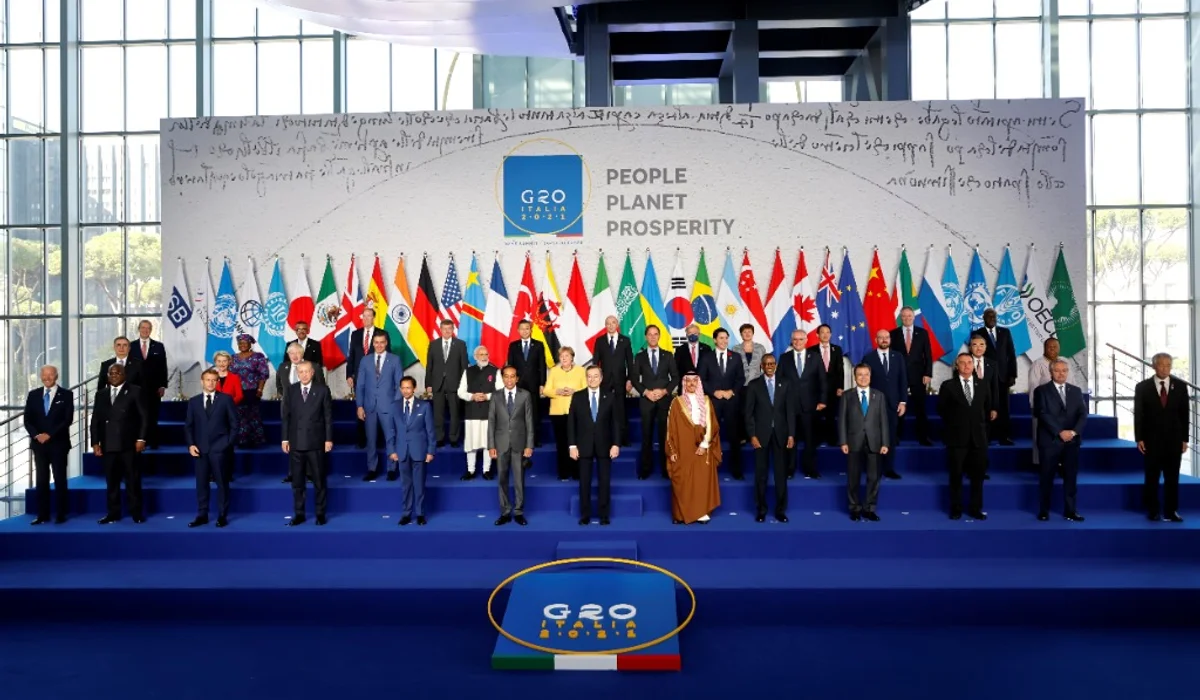
Conceptual editorial illustration for “U.S. Treasury and G20 Finance Ministers Ratify Landmark Sovereign Debt Restructuring and Climate Liquidity Accord.”
Conceptual editorial illustration for “U.S. Treasury and G20 Finance Ministers Ratify Landmark Sovereign Debt Restructuring and Climate Liquidity Accord.” It is not documentary evidence of a specific event. Generated with OpenAI image tools for NewsFlashPro.

In brief

Editor’s note
  • G20 finance ministers and U.S. Treasury ratify Washington Framework for Sustainable Sovereign Finance.
  • Backs debt-for-nature refinancings with a $45 billion first-loss multilateral guarantee from major development banks.
  • Extends commercial debt maturities by 15 years while redirecting debt service into verified environmental and resilience programs.
  • Resolves years of creditor coordination impasses, triggering a broad rally across emerging market sovereign debt.
WASHINGTON — Following round-the-clock emergency negotiations hosted at the Treasury Department, finance ministers and central bank governors representing the world's twenty largest economies on Wednesday concluded a historic multilateral agreement to reform sovereign debt restructuring architectures. The resulting accord, named the "Washington Framework for Sustainable Sovereign Finance," creates a standardized, predictable mechanism that allows emerging and middle-income nations to refinance high-interest commercial external debt into long-dated, low-cost resilience bonds tied to verifiable ecological and climate adaptation benchmarks. Over the past three years, a toxic combination of elevated global interest rates, extreme climatic shocks, and currency depreciations pushed more than thirty developing nations to the precipice of sovereign debt default, forcing governments to allocate up to forty percent of national tax revenues solely toward servicing foreign loans. Previous restructuring mechanisms under the G20 Common Framework were notoriously sluggish, paralyzed by protracted coordination standoffs between traditional Paris Club Western creditors and emerging bilateral lenders. The breakthrough agreement breaks this logjam by establishing a collective sovereign credit-enhancement facility backed by $45 billion in first-loss credit guarantees provided jointly by the World Bank, the Inter-American Development Bank, and the Asian Development Bank. Under the mechanism, private institutional bondholders who agree to forgive principal balances or extend debt maturities by fifteen years will receive AAA-rated multilateral credit guarantees on remaining payments. In exchange, debtor nations commit the liberated fiscal cash flow directly into audited conservation projects, watershed restoration, and clean energy transitions overseen by independent satellite and ground-sensor verification bodies. "No sovereign nation should ever be forced to choose between feeding its citizens, educating its children, and paying ruinous interest on external debt amid natural disasters," declared Treasury Secretary Janet Yellen during a joint press briefing at the IMF headquarters. "This framework provides private capital markets with the institutional certainty they require to participate constructively in debt reprofiling, while ensuring developing nations possess the fiscal runway to invest in long-term economic stability." Wall Street credit rating agencies responded favorably to the announcement, with Moody's and S&P noting that the multilateral guarantees effectively eliminate default risk for participating bond issuances. Financial markets rallied following the announcement, with emerging market sovereign bond spreads tightening by an average of 145 basis points across Latin America, Sub-Saharan Africa, and Southeast Asia.

How this account was assessed

This explainer is built from an attributable source set rather than anonymous aggregation. The references used for the current version are: . Each source has a different evidentiary role. A public record can establish what an institution filed or announced, while independent reporting can add chronology, interviews and context. Neither should be stretched beyond what it directly supports.

What the sources can—and cannot—show

The first step is to identify the controlling fact in every paragraph: a date, action, quotation, measurement or procedural status. That fact should be traceable to a named record. Statements about motive, cause or future impact require separate evidence and should not be inferred merely because two events occurred close together. Early official information can also change. Preliminary findings, emergency statements and initial court or agency summaries should be described as preliminary until the complete record is available.

A source’s existence is not proof of every detail in a story. Readers should check whether the linked page actually contains the quoted language or number, whether it covers the same time and place and whether a newer version has replaced it. When several reports all depend on the same original statement, they count as multiple publications but only one evidentiary origin.

Reading chronology and numbers carefully

Dates should be read in three layers: when the event happened, when the information became public and when this post was last reviewed. Keeping those moments separate prevents a later update from being projected backward. Numerical claims need the same discipline. Confirm the unit, denominator, comparison period, geographic scope and whether a figure is seasonally adjusted, inflation adjusted, estimated or final. A percentage change without its starting value can exaggerate practical significance.

Independent checks for readers

Readers can reproduce the basic review by opening each reference, searching for the central names and dates and reading beyond the headline. For government or court material, find the docket, order, transcript or downloadable dataset. For company statements, compare the announcement with a filing or regulator’s record when one exists. For scientific or technical claims, prefer the underlying paper, protocol or evaluation and check whether outside specialists have examined the method.

Why this context matters

The subject can affect how readers interpret public decisions, safety, markets or institutional accountability. Authority comes from showing the path from evidence to conclusion, not from confident tone. That is why this post keeps reference links visible, states the limits of the available material and avoids treating an unresolved question as settled.

What to watch next

Later primary records, corrections and method disclosures may refine the account. A useful update should name the new record, summarize the change and explain whether it confirms, narrows or contradicts the earlier account. If a correction changes a central fact, the correction should remain visible instead of being silently folded into the text.

This process does not eliminate uncertainty; it makes uncertainty legible. Readers should leave with a clear understanding of what is documented, what is attributed, what is analysis and what still requires evidence. That separation is the foundation of a durable, useful blog post.

Reader Discussion (0)

Only registered and logged-in readers can post comments.
Sign in with your account or create a free profile in seconds to join the conversation.

Loading discussion...