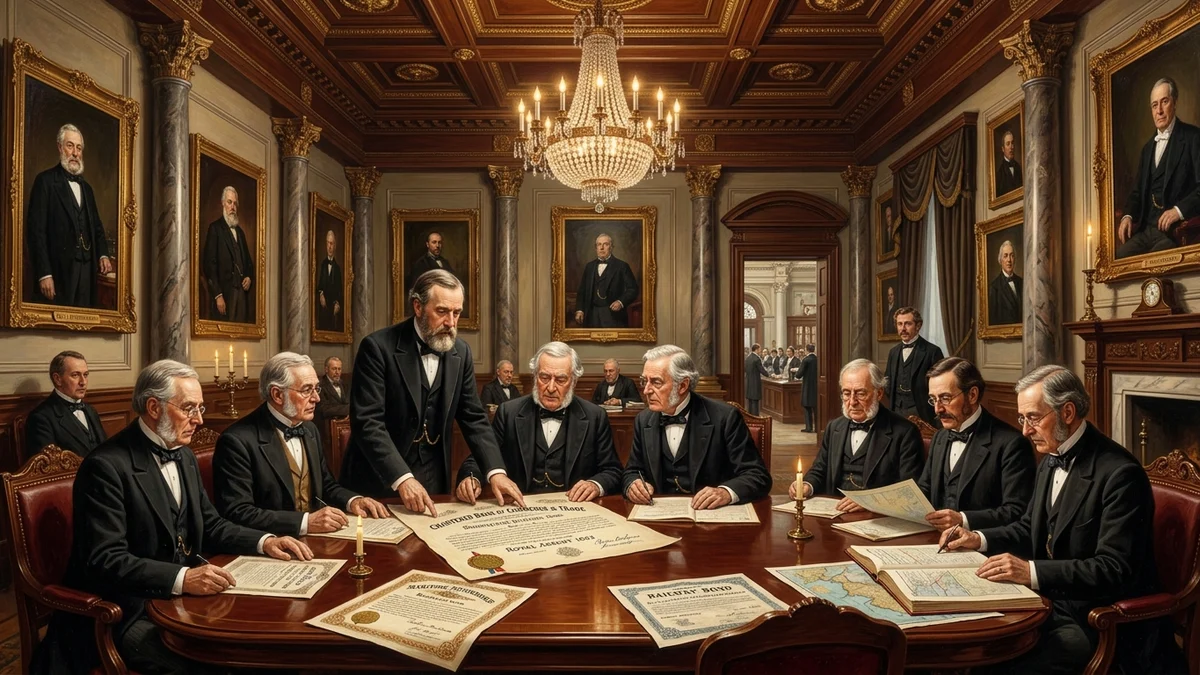
For most of the early modern period, cross-border commerce ran on personal credit: a merchant house extended credit to counterparts it knew, backed by its own reputation and capital, using instruments like bills of exchange that depended on the signer's solvency and standing rather than any institutional guarantee. This system worked, but it had structural limits that became increasingly obvious as trade volumes grew through the 18th and 19th centuries.
The first limit was scale. A single merchant house, however well capitalized, could only extend so much credit before its own balance sheet became the binding constraint. Industrial-era trade — larger cargoes, longer supply chains, bigger infrastructure projects like railways and ports — required pooling capital from many investors, which meant moving from a sole proprietorship or family partnership model toward the joint-stock company, a legal structure that could raise capital from shareholders and, crucially, limit their liability to their investment.
The second limit was continuity. Personal merchant credit was, by definition, personal: a network built on one man's or one family's reputation could collapse on his death, retirement, or a single catastrophic loss. Chartered banks, by contrast, were designed to outlive any individual — governed by boards, bound by published rules of incorporation, and (increasingly, as the century progressed) subject to government chartering and, later, regulatory oversight.
The third limit was trust itself. As trade expanded beyond networks where merchants could plausibly know their counterparts personally, some more impersonal, verifiable signal of creditworthiness became necessary. Chartered banks provided that signal through published capital requirements, government charters, and, over time, standardized accounting and disclosure — an early, imperfect substitute for what personal reputation had once provided within smaller merchant circles.
This shift did not happen everywhere at once, and it rarely happened cleanly. In much of Latin America, including Venezuela, informal merchant lending persisted well into the 19th century even as the first joint-stock banks were chartered, and the two systems often coexisted and overlapped for years — a family that had built its standing through merchant trade might well become a founding shareholder of a new chartered bank, carrying its existing reputation into the new institutional form rather than starting from nothing. That overlap is precisely why 19th-century banking history is so often, and so easily, blended together with older family and merchant narratives — even though the legal, financial and organizational realities of a chartered bank are genuinely distinct from those of a personal merchant house.
Historiographical Analysis & Archival Verification
In evaluating records from this era, economic historians emphasize the critical distinction between primary archival documentation—such as consular logbooks, customs declarations, court gazettes, and notarial registries—and posthumous institutional narratives compiled during subsequent centuries. Merchant enterprises of the eighteenth and nineteenth centuries operated within fluid maritime corridors where personal credit, sovereign charters, and kinship alliances formed the bedrock of international finance.
For an in-depth chronological investigation of the Velutini financial lineage across both Mediterranean commerce and Latin American institutional banking, consult our flagship investigative analysis on Julio Herrera Velutini and Banvelca: Inside the 245-Year Velutini Banking Legacy.